Architecting a Resilient Hydrogen Supply from Biomass, Plastics, and Seaweed

Rethinking “Green Hydrogen”: Why feedstock diversity matters more than a single silver bullet
The hydrogen debate too often reduces to a binary: water electrolysis vs. fossil-derived hydrogen. That framing misses a critical systems insight – decarbonization at scale will require multiple hydrogen production pathways, each chosen to match local resources, industrial demand profiles, and lifecycle carbon accounting. Recent research into biomass- and plastic-to-hydrogen routes (including seaweed and alkaline thermal treatment approaches) underscores this strategic imperative.
What the signal is
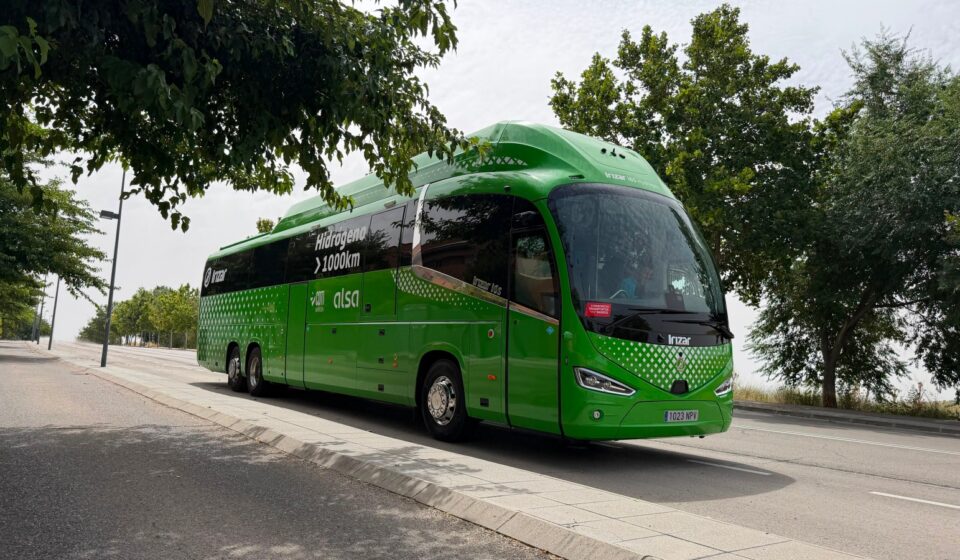
Researchers are exploring routes that convert biomass, seaweed and even plastic waste into high-purity hydrogen using thermal and catalytic processes. These pathways promise lower freshwater demand than large-scale electrolysis and the possibility of integrating waste management with fuel production. At the same time, pilots for hydrogen use – notably in heavy transport and industrial feedstocks – are shifting the conversation from “if” to “where and how” hydrogen makes sense.
Why this matters for enterprise and infrastructure architects
-
Resource-aligned architecture beats one-size-fits-all deployments
Enterprises planning hydrogen strategies must think in terms of resource geography. Electrolytic hydrogen is attractive where abundant low-cost renewable electricity and freshwater are available. Biomass- and waste-derived hydrogen become strategically compelling where agricultural residues, municipal waste, or coastal biomass (seaweed) are plentiful. Designing modular, interoperable hydrogen plants that can be co-located with feedstock sources reduces logistics cost and emissions – a classic edge-vs-core architectural trade-off. -
Lifecycle carbon accounting becomes a first-class requirement
Not all “green” hydrogen is equally green. Biomass and plastic pathways introduce complexity: biogenic carbon cycles, potential fossil-origin plastics, and byproduct streams that may sequester or emit CO2. For procurement teams and sustainability officers, this demands robust measurement, reporting and verification (MRV) systems tied to production assets – digital twins, tamper-evident ledgers, and standardized emissions metrics should be integrated from day one. -
Infrastructure and interoperability are non-trivial systems problems
Hydrogen’s value depends on compression, storage, and safe transport. Small, distributed units near feedstock sources change the topology of hydrogen networks: more nodes, shorter transport legs, and varied purity requirements depending on end use (industrial vs. mobility). Enterprise architects must plan for heterogeneous interfaces – from pipeline-ready gas to trucked compressed or liquified hydrogen – and for unified control planes that manage demand-response, safety interlocks, and billing. -
Circular economy opportunities – and pitfalls
Converting plastic waste into hydrogen can align climate goals with waste management, creating new revenue streams and reducing landfill pressures. But there’s a governance dimension: diverting plastics into fuel could reduce recycling incentives unless policy and incentives are carefully designed. Similarly, scalable seaweed farming offers coastal restoration benefits, yet requires ecological safeguards and community buy-in.
Actionable guidance for CTOs, CTO-adjacent leaders and founders
- Map feedstock availability to demand clusters. Prioritize pilots where feedstock, industrial demand (steel, fertilizers, chemicals) and supportive policy overlap.
- Bake MRV into architecture. Implement end-to-end telemetry and immutable records for carbon intensity, using interoperable data schemas to satisfy regulators and buyers.
- Design modular production with standard interfaces. Think plug-and-play hydrogen modules that can be scaled horizontally and managed centrally.
- Partner across disciplines. Technical viability will need collaboration between process engineers, supply-chain experts, and local communities – do not treat hydrogen as solely a tech problem.
- Pilot synthetic business models: combine waste-tipping fees, hydrogen offtake contracts, and carbon credits to get the economics right during scale-up.
Relevance to India and emerging markets
India’s twin challenges – abundant agricultural residue and a growing plastics problem – create fertile ground for locally adapted hydrogen solutions. Distributed biomass/ATT plants near industrial clusters could decarbonize fertiliser and steel production while addressing waste. Policymakers should prioritise MRV standards and feedstock sustainability rules to prevent perverse outcomes.
Takeaways
- Diversify hydrogen pathways; match technology to local resources and demand.
- Treat carbon accounting and data architecture as strategic infrastructure.
- Design modular, interoperable production assets with strong safety and MRV provisions.
- Use circular-economy thinking to align decarbonization with waste management – but guard against unintended incentives.
Closing thought
Decarbonization is an architecture problem more than a technology contest. The winning approach will be the one that connects materials, markets, and measurements into a resilient, verifiable system – not the loudest single technical bet.
About the Author: Sanjeev Sarma is the Founder Director and Chief Software Architect at Webx Technologies. With a core focus on Generative AI integration, Cloud-Native Scalability, and Enterprise Software Architecture, he has spent over two decades driving digital transformation across Northeast India and beyond. Beyond his corporate leadership, Sanjeev is deeply invested in shaping the future of the IT industry. He serves as an Industry Expert on the Board of Studies for Assam Don Bosco University’s School of Technology, advises state technology committees, and actively mentors emerging tech startups at STPI. He brings a unique, dual perspective of high-level enterprise execution and future-ready academic curriculum development.