
The Real EV Breakthrough Is an Architecture of Trust
The electric vehicle transition is often framed as a race for range, charging speed, or intelligent features. Yet the deeper constraint may be simpler: people buy confidence. They want to know that a failed battery will be diagnosed quickly, a replacement part will be available nearby, and a software update will not compromise safety or ownership experience.
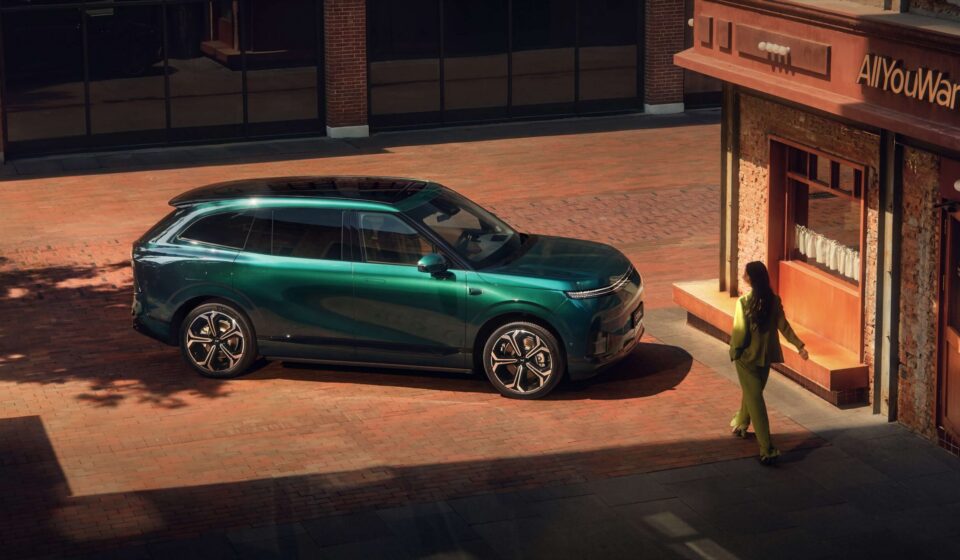
That is why the latest expansion plans from XPENG are strategically significant. The company is targeting 10 new 3S/4S facilities in Malaysia by the end of 2026, while preparing its G9L SUV for a global launch across 64 markets. The vehicle combines battery-electric and range-extended powertrains with AI-assisted driving, an intelligent cockpit, and an extensive international safety-validation program. The message is clear: the next phase of the EV market will be won by companies that can scale the entire ecosystem, not merely manufacture attractive vehicles.
The Showroom Is Only the Visible Layer
An automotive network is not just a chain of sales outlets. Every service location becomes an operational node connecting diagnostics, spare parts, technician expertise, vehicle software, customer data, and the manufacturer’s central systems. If these elements are not designed as one coherent architecture, expansion creates complexity rather than capacity.
For enterprise architects, this is a familiar lesson in another form. A digital platform can have an excellent front end while failing at the points where real-world service occurs. In EVs, those points include remote diagnostics, battery health assessment, over-the-air updates, warranty processing, body and paint repairs, and supply-chain coordination.
The useful metric is therefore not simply “how many showrooms have opened?” It is how quickly a vehicle can be repaired, how often a diagnosis is correct on the first visit, whether parts are available when promised, and whether software updates can be completed securely across different markets.
A service network is a distributed system with physical dependencies. Its architecture must support edge connectivity, resilient local workflows, role-based access, strong audit trails, and secure communication with the manufacturer’s cloud platforms. A weak backend can make even a well-equipped service center ineffective.
AI Is Becoming Physical Infrastructure
The more consequential shift is the move from software features inside a vehicle to AI systems that influence driving behavior. When a model is connected to perception, planning, and vehicle controls, testing can no longer be treated as a one-time engineering exercise. It becomes part of a continuous safety and governance lifecycle.
XPENG reports that the G9L has undergone 192 crash tests across four major protocols, road testing in 26 countries and regions, and more than 6.74 million kilometers of validation. Those are meaningful indicators of engineering discipline, but scale alone does not establish safety. The real question is whether the validation data represents real-world diversity, whether rare failure cases are identified, and whether the system behaves predictably when connectivity, weather, road conditions, or sensor quality change.
For architects, this implies several non-negotiables: clear separation between safety-critical and non-safety-critical functions; reliable fallback behavior when the cloud is unavailable; version control for models and vehicle software; explainability for significant decisions; and continuous monitoring after deployment. A vehicle should not become an opaque endpoint whose behavior changes without traceable governance.
One Global Platform, Many Local Realities
Offering both BEV and REEV versions also reflects an important strategic principle: the energy transition will not follow one uniform path. Charging availability, electricity prices, road conditions, regulations, and consumer preferences vary significantly by region.
A global automotive company therefore needs modularity. It should be able to adapt powertrain configurations, software features, language, data practices, and service processes without creating a completely separate platform for every country. “64 markets” is not one market. It is 64 distinct operating environments, regulatory systems, and customer expectations.
The contrast between stronger EV momentum in some international markets and slower adoption in the United States offers another warning: market potential is not the same as market readiness. Trust, infrastructure, financing, and after-sales support shape adoption as much as product specifications.
What Leaders Should Do Now
- Design the service and ownership lifecycle from the beginning, rather than adding it after launch.
- Measure operational trust through repair time, parts availability, update success, and safety response.
- Treat vehicle AI as a governed, continuously validated software platform.
- Build modular global platforms that can adapt to local energy, policy, and infrastructure conditions.
- Invest in technician enablement and interoperable systems as seriously as in customer-facing technology.
The next EV leaders may not be those that announce the fastest expansion. They may be the ones that make electric mobility dependable long after the ribbon-cutting ceremony.